Free Cash Flow: What It Reveals About the Cash a Business Can Actually Deploy
Free cash flow measures cash generated after the spending required to maintain and grow the operating asset base, though definitions differ by analytical purpose.
Editorial standard: This guide is designed as a long-form reference. It separates definitions from judgments, uses worked examples and trade-offs, and links the concept to the broader Millionaire Lesson system.
1. What the concept actually means
Free cash flow measures cash generated after the spending required to maintain and grow the operating asset base, though definitions differ by analytical purpose. The important analytical move is to separate the label from the mechanism. People often use the phrase free cash flow as if it described a single number or rule, but the useful version is a system of inputs, trade-offs, incentives, and constraints. A high-quality decision therefore begins by asking what drives the outcome, what can break, and which variables are actually controllable.
Viewed through a financial lens, the central question is whether the decision improves the system after accounting for constraints. For free cash flow, that means refusing to evaluate the choice in isolation. A decision that looks attractive before financing, taxes, customer response, implementation cost, or behavioral risk may become unattractive after those factors are included. This is why disciplined analysis often feels slower at the beginning but faster later: it prevents the organization or household from spending years correcting an avoidable structural mistake.
A fast-growing company can report accounting profit while producing negative free cash flow if working capital and capital expenditures consume cash. This example matters because it shows why surface-level descriptions can be misleading. Two situations that look similar on a spreadsheet can have different liquidity, time horizons, concentration, bargaining power, or behavioral risk. The best analysis moves from headline numbers to the structure underneath them.
2. Why this topic matters in real decisions
The value of understanding free cash flow is not academic. It changes how people allocate scarce resources. Households and investors must decide how much to spend, save, hold liquid, borrow, insure, and expose to market risk. A weak model can produce years of apparently reasonable behavior that fails under stress.
The concept also creates a language for trade-offs. Financial decisions become clearer when opportunity cost, liquidity, concentration, and downside are explicit. Strategic decisions become clearer when customer value, cost position, differentiation, imitation, and resource fit are explicit.
3. The mechanism underneath the headline
A useful way to analyze free cash flow is to trace the chain from input to outcome. Start with the resources and constraints. Then identify the behavior or operating mechanism. Next, measure the intermediate result. Finally, ask whether the final outcome remains attractive after fees, taxes, risk, competition, or implementation cost.
For personal finance, this prevents a common error: optimizing a visible variable while weakening the system. A higher return is not better if it requires ruinous leverage; a larger net worth is not more useful if it cannot fund obligations; a higher income is not wealth if every dollar is pre-committed.
4. The numbers and measures that matter
The core relationship can be summarized as FCF to firm ≈ EBIT×(1−tax rate) + D&A − capex − change in working capital. The formula is not the whole concept, but it forces the main variables onto the page. A good model uses realistic assumptions, scenario ranges, and after-tax or after-cost values where appropriate.
Useful measures usually include a stock measure, a flow measure, and a risk measure. The stock tells you what exists now; the flow shows what the system is producing or consuming; the risk measure shows how fragile the outcome is to a change in conditions.
5. A worked example
A fast-growing company can report accounting profit while producing negative free cash flow if working capital and capital expenditures consume cash. Now extend the example. The first-order result is easy to see, but the second-order consequences often matter more. What happens if income falls, interest rates change, customer demand weakens, a competitor responds, or an asset cannot be sold quickly? The point of a worked example is not to predict every future state; it is to reveal which variables deserve monitoring.
A robust financial decision would compare at least a base case, downside case, and liquidity-stress case. A robust strategic decision would compare a base competitive response, an aggressive response, and a substitution scenario. The quality of the decision comes from seeing the system before committing irreversibly.
6. Common mistakes
The most common mistakes are not always technical; many are behavioral. People anchor to purchase prices, recent returns, peer lifestyles, market narratives, or a favored strategic story. Once identity becomes attached to a decision, updating becomes harder.
A second class of mistakes comes from denominator blindness: looking at revenue without capital required, return without risk, wealth without liabilities, growth without unit economics, or customer count without retention.
- One year’s FCF can be distorted by working capital.
- Cutting necessary capex can temporarily inflate cash flow.
- Stock-based compensation and acquisition spending require separate judgment.
1. One year’s FCF can be distorted by working capital.
This point matters because it changes the decision boundary. In practice, one year’s fcf can be distorted by working capital. For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
2. Cutting necessary capex can temporarily inflate cash flow.
This point matters because it changes the decision boundary. In practice, cutting necessary capex can temporarily inflate cash flow. For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
3. Stock-based compensation and acquisition spending require separate judgment.
This point matters because it changes the decision boundary. In practice, stock-based compensation and acquisition spending require separate judgment. For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
7. A decision framework you can actually use
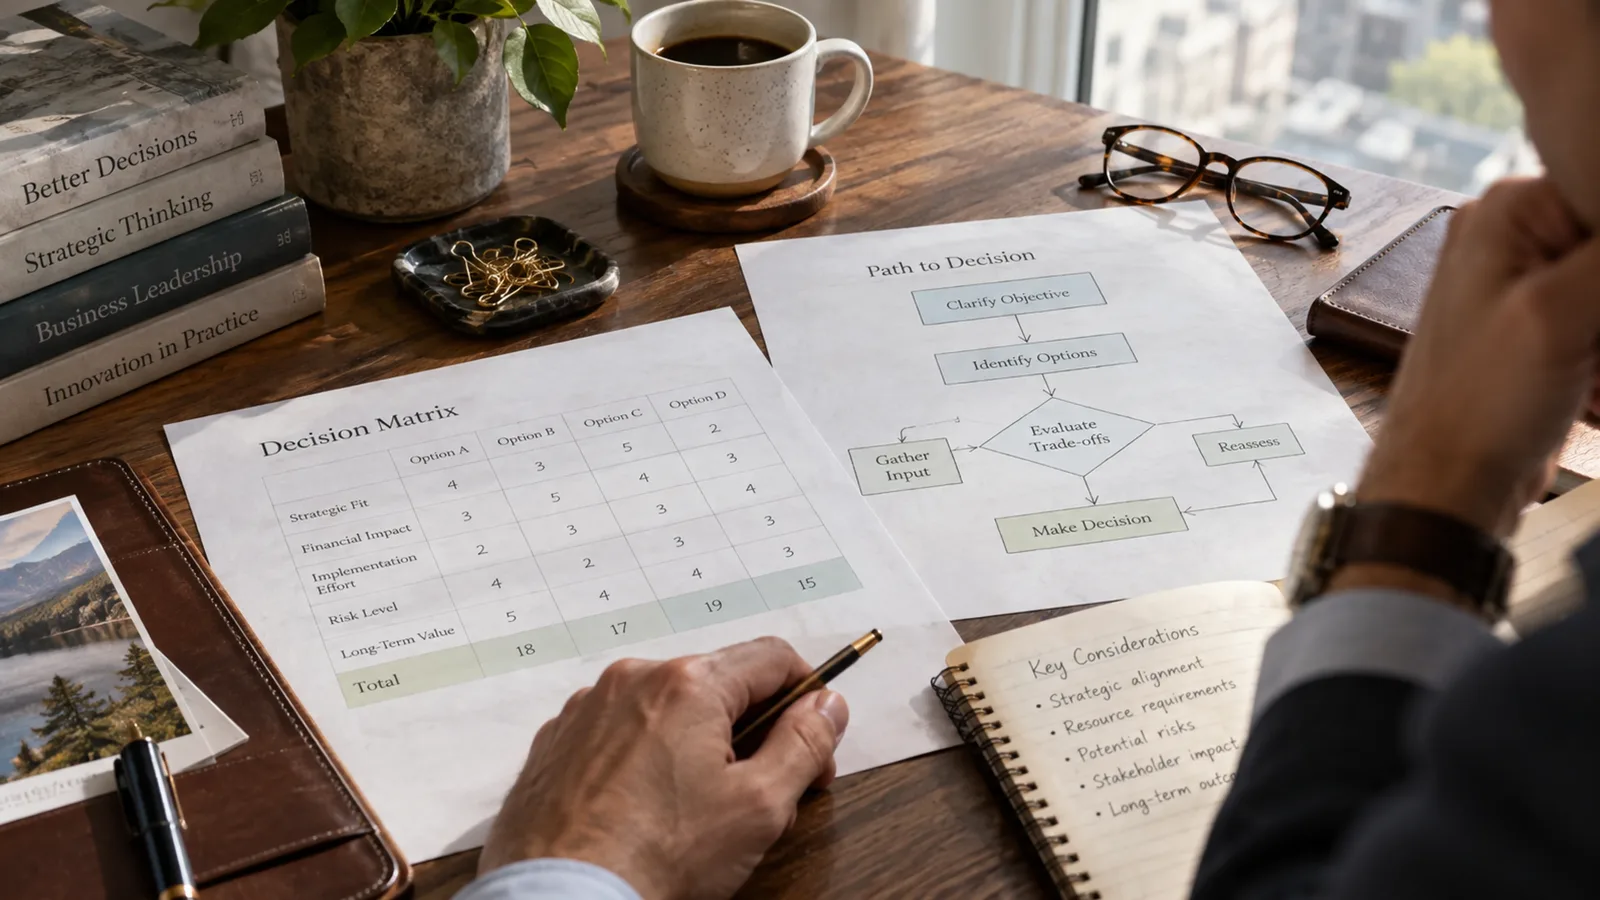
Use a five-step framework. First, define the decision and time horizon. Second, identify the variables that genuinely drive the outcome. Third, quantify what can be quantified without pretending the estimate is precise. Fourth, test a downside state. Fifth, define the condition that would make you change course.
The final step is especially important. Decisions often fail because people decide only how to start, not how to stop, rebalance, refinance, sell, narrow scope, or abandon a thesis.
- Normalize cash flow across a business cycle.
- Reconcile earnings to cash.
- Study what management does with the cash after it is generated.
1. Normalize cash flow across a business cycle.
This point matters because it changes the decision boundary. In practice, normalize cash flow across a business cycle. For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
2. Reconcile earnings to cash.
This point matters because it changes the decision boundary. In practice, reconcile earnings to cash. For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
3. Study what management does with the cash after it is generated.
This point matters because it changes the decision boundary. In practice, study what management does with the cash after it is generated. For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
8. Trade-offs and second-order effects
Every advantage associated with free cash flow has a cost. Safety can reduce upside; leverage can increase fragility; specialization can shrink the addressable market; diversification can dilute concentration in the best opportunity; premium positioning can narrow volume. Good judgment does not search for a choice with no downside. It looks for a trade-off that fits the objective.
Second-order thinking asks what happens after the obvious result. If everyone copies the same strategy, does the advantage disappear? If a household raises lifestyle after every income gain, does a higher salary actually increase freedom? The question is not only ‘what happens next?’ but ‘what happens after everyone reacts to what happens next?’
9. What changes in a bad environment
Financial systems that look comfortable in stable periods can break when liquidity dries up, income falls, inflation changes, or correlations rise. Stress reveals whether the plan depended on continuous refinancing, optimistic valuations, or perfect behavior.
A good plan is therefore not optimized only for the expected case. It retains enough flexibility to survive ordinary surprise.
10. How behavior changes the outcome
Financial outcomes are path dependent because humans act inside the system. Selling during panic, levering after a boom, chasing recent winners, or expanding fixed expenses after a raise can overwhelm a sound mathematical plan.
Process design is therefore part of the solution. Automation, precommitment, review schedules, independent challenge, and explicit thresholds reduce the number of important decisions made in the heat of emotion.
11. A practical checklist
Before acting, write the objective in one sentence. Then write the three variables that matter most, the two ways the plan could fail, and the one condition that would make you stop or change course. This simple exercise is more useful than adding another page of analysis that does not change the decision.
After implementation, schedule a review based on evidence rather than mood. Good decisions can have bad short-term outcomes, and bad decisions can get lucky. Review the logic, assumptions, and process—not only the result.
- What is the objective and time horizon?
- Which variable drives most of the outcome?
- What is the realistic downside?
- What would force a sale, stop, pivot, or reallocation?
- Which assumptions are facts, and which are forecasts?
1. What is the objective and time horizon?
This point matters because it changes the decision boundary. In practice, what is the objective and time horizon? For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
2. Which variable drives most of the outcome?
This point matters because it changes the decision boundary. In practice, which variable drives most of the outcome? For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
3. What is the realistic downside?
This point matters because it changes the decision boundary. In practice, what is the realistic downside? For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
4. What would force a sale, stop, pivot, or reallocation?
This point matters because it changes the decision boundary. In practice, what would force a sale, stop, pivot, or reallocation? For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
5. Which assumptions are facts, and which are forecasts?
This point matters because it changes the decision boundary. In practice, which assumptions are facts, and which are forecasts? For free cash flow, the best response is to make the assumption explicit, test it with evidence, and avoid confusing a temporary favorable outcome with proof that the underlying logic is sound.
12. How this connects to the rest of the system
free cash flow is not an isolated topic. It connects to saving rate, liquidity, diversification, risk tolerance, opportunity cost, and capital allocation. A household or investor becomes stronger when these pieces reinforce one another instead of being optimized independently.
This systems view is the main reason deep understanding matters. The concept is useful not because it provides a clever definition, but because it improves the quality of connected decisions.
13. Three scenarios that change the answer
Scenario A — favorable conditions. Assume the core assumptions behind free cash flow hold, liquidity is adequate, and implementation is disciplined. In this case the concept can work close to the textbook model. The danger is overlearning from an easy environment and assuming the same behavior will work when conditions change.
Scenario B — stress. Now assume a recession, market drawdown, customer slowdown, financing shock, or execution failure. The important question is whether the system built around free cash flow survives without a forced decision. Fragility becomes visible when a plan requires continuously favorable conditions.
Scenario C — opportunity. Finally, assume an unusually attractive alternative appears. A strong system should preserve enough liquidity, attention, or strategic capacity to act. Opportunity is valuable only if prior commitments have not consumed every resource.
14. A case-study method for using this article
Take one real decision involving free cash flow and write a one-page case. Start with the current state, constraints, and objective. Add the relevant numbers. Then write the strongest argument for action and the strongest argument against it. The objective is not to create false balance; it is to expose which assumptions carry the most weight.
Next, build a pre-mortem: imagine the decision failed badly two years from now. What most likely caused the failure? Then imagine it worked unusually well. What mechanism created the upside? The gap between those two stories often reveals the variables worth monitoring.
Finally, convert the analysis into a rule. Rules are useful because they reduce the number of future decisions that must be made under stress. A good rule is specific enough to guide behavior but flexible enough to update when evidence changes.
Frequently Asked Questions
What is free cash flow?
Free cash flow measures cash generated after the spending required to maintain and grow the operating asset base, though definitions differ by analytical purpose.
Why does free cash flow matter?
It matters because it changes how scarce resources are allocated and how risk is absorbed. For households and investors, weak decisions can reduce liquidity, compounding, or resilience.
What is the biggest mistake people make with free cash flow?
One year’s FCF can be distorted by working capital.
How should someone apply free cash flow in practice?
Normalize cash flow across a business cycle.
Is free cash flow always beneficial?
No. The concept describes a tool or relationship, not a guarantee. Its value depends on context, constraints, implementation quality, and opportunity cost.
Related Reading on Millionaire Lesson
Wealth vs Income →
Cognitive Biases →
Decision-Making Models →
Wealth vs Net Worth: The Difference Between a Number and a Financial System →
Wealth Psychology: How Beliefs, Status, Risk, and Time Shape Financial Behavior →
Compounding Wealth: How Reinvestment Turns Small Advantages Into Large Gaps →
Sources and Further Reading
- CFA Institute cash-flow analysis
- Aswath Damodaran valuation materials
- SEC financial statement guidance